Quick Withdrawal Casinos in Australia: Payment Guide
 Available in AU
A payment method’s transfer speed is only part of the picture: withdrawal availability, release steps and account checks also matter.
Table of Contents
- How payment methods affect cashout speed
- Why a withdrawal can take longer than the payment itself
- What changes when you withdraw slot winnings
- When a casino releases a withdrawal
- How PayID transfers work in Australia
- Limits, fees and the details to check before withdrawing
- Real-money withdrawals and matching payment details
- How to assess claims about fast withdrawals
- Why ‘no verification’ does not mean no checks
- Online slots: checks that can interrupt a cashout
How payment methods affect cashout speed
The payment route determines how funds travel after they have been sent, but a method used to add money is not necessarily available for receiving it. For Australian readers, there is also an important legal boundary: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including slots, to people physically located in Australia. The comparisons below describe payment mechanics, not a recommendation to use such a service.
Payment options reported for casino platforms include cards, e-wallets and bank transfers, with cryptocurrency available on some platforms. A specialist review also describes instant banking services such as POLi at some real-money platforms. These are not interchangeable routes: they differ in whether they can receive withdrawals and in how quickly a transfer may complete.
E-wallets
PayPal and Skrill are examples of e-wallets. Where a platform supports withdrawals to an e-wallet, the transfer does not need to follow the same path as a conventional bank payment. A specialist review describes e-wallet transactions as completing within hours rather than days. Another general payment-time estimate puts e-wallet withdrawals within 24 hours. These are reported timeframes, not a guarantee for a particular transaction.
If you need a quick withdrawal, check what payout timing is actually stated before choosing a casino. This list highlights the available details so you can focus on what is known rather than assume a withdrawal speed.
License: Curacao · Min. deposit: A$20 (POLi) Lucky Dreams lists a minimum deposit of A$20 via POLi and a Curacao license. No withdrawal speed is specified here, so you should confirm payout timing before relying on it for a quick cashout.
License: Curacao OGL/2024/1335/0780 · Min. deposit: EUR 20 Vegaz Casino lists Curacao OGL/2024/1335/0780 and a minimum deposit of EUR 20. The available details do not state withdrawal speeds, so check the payout terms if timing is important to you.
License: Curacao Golden Pokies is listed with a Curacao license. No payout timing or other operator details are provided here, so you should verify the withdrawal terms before choosing it for speed.
License: Curacao eGaming (Roby Games Ltd) Roby Casino is listed under Curacao eGaming, with Roby Games Ltd named as the operator. No withdrawal speed is specified in the available details.
Payout speed: crypto under 1 hour, PayID 1-3 business days · Min. deposit: A$20 (A$30 to qualify for the bonus) Ricky Casino lists crypto payouts under 1 hour and PayID payouts in 1–3 business days. Its minimum deposit is A$20, or A$30 to qualify for the bonus.
License: Curacao eGaming (Hollycorn N.V., since 2017) · Min. deposit: A$20-30 (depends on the offer) Playfina Casino is listed under Curacao eGaming, with Hollycorn N.V. operating since 2017. Its minimum deposit is A$20–30 depending on the offer; no withdrawal speed is stated here.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) LuckyVibe is listed under Curacao Gaming Control Board OGL/2023/176/0095, with Hollycorn N.V. named. The available details do not specify payout timing, so check that information directly if you need a quick withdrawal.
License: Curacao (operating since 2017) · Min. deposit: A$20 Uptown Pokies is listed as operating since 2017 under a Curacao license, with a minimum deposit of A$20. No withdrawal speed is provided in the available details.
License: Curacao Gaming Control Board JustCasino is listed with a Curacao Gaming Control Board license. No withdrawal timing or other details are provided here, so verify its payout terms before relying on it for speed.
License: Curacao Gaming Control Board OGL/2023/174/0082 (Dama N.V.) SpinsUp is listed under Curacao Gaming Control Board OGL/2023/174/0082, with Dama N.V. named. The available details do not state how quickly withdrawals are processed.
An e-wallet is useful for cashout comparison only if it is enabled for withdrawals, not merely listed as a deposit option. Check the platform’s payment terms for the outgoing route and any stated processing window. The name of a wallet alone does not establish how quickly funds will arrive: the receiving wallet, the operator’s payment arrangement and the applicable terms all matter.
Bank transfers and instant banking
A traditional bank transfer can involve a longer wait than an e-wallet transfer. One specialist review reports that completion may take as long as five business days. A separate general estimate describes bank payments as potentially taking several days. These figures are reported descriptions, not universal service standards; bank processing schedules and the specific transfer route affect the outcome.
Instant banking services are a distinct category. Some real-money platforms have been reported to offer services such as POLi, but that does not mean every bank transfer is instant, nor does a deposit route necessarily support cashouts. Confirm whether the named service is available for withdrawals before treating it as a speed advantage.
Cards and prepaid vouchers
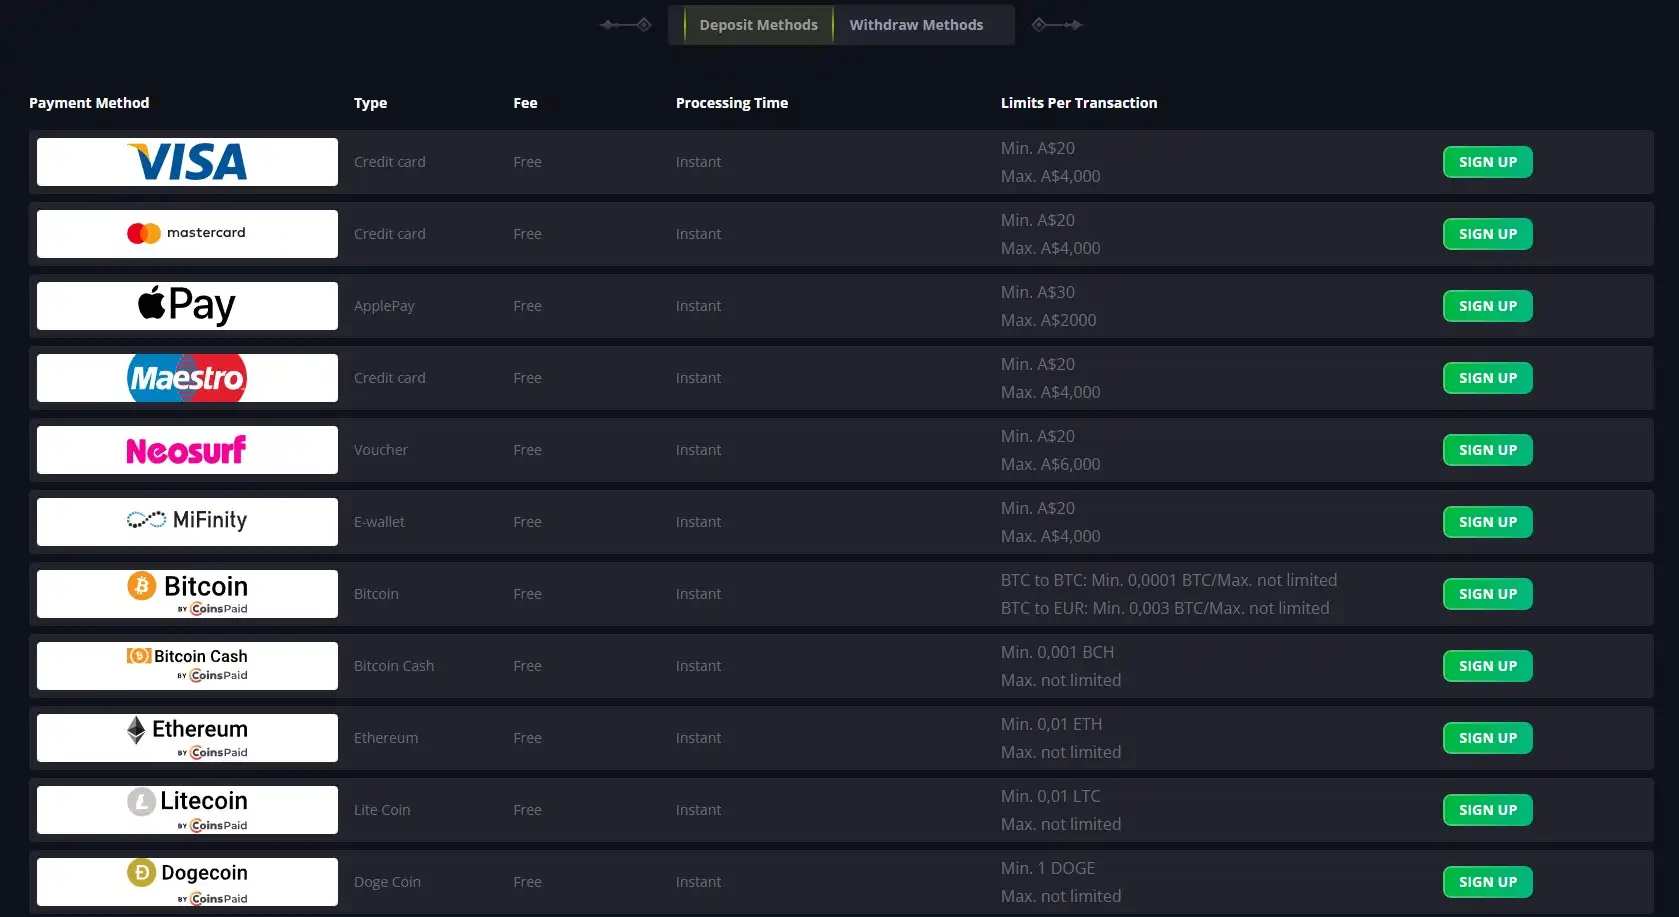
Credit and debit cards appear among the payment methods reported for casino platforms, but a card accepted for deposits is not automatically a supported withdrawal destination. For a comparison, look for a specific statement about withdrawals to the card, rather than inferring that outgoing payments work in the same way as incoming ones.
Prepaid products have a different limitation. Specialist reviews describe vouchers such as Neosurf as deposit-oriented and generally unavailable for withdrawals. A player using a voucher may therefore need another supported route to receive funds. That extra route can matter more than the speed of the original deposit method.
Cryptocurrency
Some platforms offer cryptocurrency, and one specialist review characterises crypto transactions as potentially near-instant. That description concerns the transfer itself and should not be read as a promise that every cashout will arrive immediately. It also does not establish that cryptocurrency is available at a particular platform or that it can be used for both deposits and withdrawals.
The practical comparison is therefore not simply “which method is fastest?” First establish that the method supports withdrawals. Then compare the timeframe stated for that outgoing transfer. An advertised speed for deposits, or a general claim about the payment network, does not by itself tell you when a cashout will be received.
For an online casino with quick withdrawal claims, the payment method is only one part of the comparison. E-wallets have reported shorter transfer windows than traditional bank payments, while crypto may be described as near-instant; however, each statement depends on the source and the specific service. Cards and vouchers require particular care because deposit acceptance does not prove withdrawal support. Treat any stated timing as applying only to the route and stage it actually describes, rather than as a prediction for every request.
Why a withdrawal can take longer than the payment itself
A withdrawal has two separate clocks. The first runs while the operator reviews the request and decides whether to send it. The second starts when the payment is released and the provider or banking network moves the funds. A fast transfer method affects the second clock; it cannot remove time spent in the first.
A withdrawal involves two separate clocks: one for the operator’s internal review and another for the actual transfer through the payment network. A fast payment method only affects the second clock.
This distinction explains why the phrase “instant withdrawal” can be misleading if it is read as a promise about the whole journey. A specialist review reported that some sites advertising instant withdrawals still took up to 24 hours because of internal review. In that situation, the payment method may transfer funds quickly once the request is approved, while the preceding review accounts for much of the elapsed time.
The review stage can involve checking whether the request is complete and whether it can be processed under the operator’s rules. If information needs attention, the request may remain pending rather than being sent to the payment provider. That status does not mean the transfer itself is slow: it means the transfer has not yet begun. You should therefore distinguish a request marked as pending from one marked as approved or paid.
Once the operator sends the funds, the payment route becomes more relevant. E-wallet withdrawals are typically processed within 24 hours, while card payments and bank transfers may take several days. Those are separate timing expectations from the review period, not a combined guarantee for request-to-receipt time. The total wait can include both stages, and the payment provider’s handling can add time after the operator has finished its part.
For example, an e-wallet route cannot make a request immediate if it is still awaiting review. Conversely, an operator may approve a request promptly, but a card or bank transfer can still take longer to reach the account. The method and the operator’s handling affect different parts of the process, so comparing only the advertised transfer speed leaves out a key part of the timeline.
When checking a withdrawal status, look for what the status actually describes. “Pending” generally points to a request that has not completed the operator’s handling; “approved” or “sent” indicates that the payment has moved beyond that stage, though it may not yet appear in your account. If the status has not changed, contacting support can help establish whether the request is under review or whether the transfer has already been released.
Do not treat the fastest stated payment time as the expected time from clicking “withdraw” to receiving funds. That figure may describe only the transfer after approval. A realistic estimate needs to account for the operator’s review and the payment route separately, with any delay in either stage extending the overall wait.
What changes when you withdraw slot winnings
A withdrawal can only be requested from funds the account treats as available to cash out. After slot play, that may not be the same as the balance displayed on screen: if a bonus has wagering conditions, some or all of the balance may remain subject to those conditions. The key detail is what amount the terms require you to wager before the funds become withdrawable.
A specialist review reports two possible approaches: the requirement may apply to bonus funds alone, or it may apply to the combined deposit and bonus. The first approach is preferable because it leaves the deposited amount outside the wagering calculation. With a combined-balance condition, more funds are included in the amount that must be wagered before the account can treat the balance as eligible for withdrawal.
- Check if wagering applies to bonus funds alone
- Identify the base used in the wagering calculation
- Keep the terms available during play
- Infer rules from the displayed balance size
- Assume a slot session end means conditions are met
- Treat combined-balance conditions as bonus-only rules
Read the condition as a calculation
Check the bonus terms for the base used in the wagering calculation. If only the bonus is included, the deposit and bonus are treated differently for that purpose. If the terms use the combined deposit-plus-bonus total, both amounts contribute to the required wagering base. Do not infer which rule applies from the size of the displayed balance or from the fact that a slot session has ended; the wording of the condition determines it.
This distinction matters because a balance can contain money that is not yet available to withdraw. Playing slots does not, by itself, show whether the relevant condition has been completed. You need to know which funds are covered and whether the account has recorded the required wagering against them. Until the applicable condition is met, a withdrawal request may not be available for that balance.
Separate the deposit from bonus funds
Before accepting or using a bonus, identify how the terms classify the deposit, bonus funds and any winnings. Then establish whether the wagering condition applies to the bonus alone or to the combined amount. These are materially different rules, even if both are described broadly as wagering requirements.
If the calculation covers the combined total, treating only the bonus as restricted can lead you to assume that deposited funds are ready to withdraw when the terms say otherwise. Conversely, if the condition applies only to bonus funds, the deposit is not part of that particular wagering base. The terms should make this distinction clear enough for you to determine what must be completed before requesting a cashout.
Keep the terms available while you play. If the account’s balance or bonus status changes, compare it with the stated condition rather than relying on the total alone. A displayed amount is not a substitute for understanding whether the balance is classified as withdrawable or still subject to wagering.
In Australia, the legal context is also important: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including slots, to people physically located in the country. The explanation above describes how bonus wording affects withdrawal eligibility where such terms are encountered; it is not an invitation to use an online casino service.
When a casino releases a withdrawal
A withdrawal has a starting point, a release point and a receiving point. Submitting the request starts the process; it does not itself send money to your bank or payment account. The operator first has to approve the request and release the funds. Only after that hand-off can the payment method’s transfer speed affect when the money arrives.
This boundary matters when you compare a stated cashout speed with the time you actually experience. A payment route may move funds quickly after release, but that says nothing by itself about how long the request remains pending beforehand. “Instant” should therefore describe the transfer phase, not the complete interval from clicking confirm to seeing cleared funds in your account.
A specialist review reports that funds sent through PayID can move instantly once the operator releases a withdrawal. That claim concerns the period after release; it does not establish that the operator approves every request immediately. A report by filmink.com.au likewise contrasts almost-instant PayID transfers with bank transfers that can take several working days. These descriptions refer to different payment paths and do not remove the release stage.
You can use a simple sequence to interpret a status message. A request marked as submitted has reached the operator, but the funds have not necessarily been sent. A pending or under-review status indicates that the operator has not yet completed its decision. A released or paid status means the operator has authorised the transfer; from then on, the destination payment route and receiving institution determine when the funds become visible.
The wording of status labels varies, so focus on the underlying event rather than the label alone. “Approved” may mean the operator has accepted the request, while “processed” may mean it has sent the payment instruction. If the account shows that the request was released but the balance has not changed, the remaining interval is not the same as an approval wait. It is the transfer or posting stage.
A fast route cannot move money that has not been released. This is why a headline claiming a very short payment time should be read as a claim about a defined stage, unless it clearly explains that it measures the entire request-to-receipt period. The distinction also works in reverse: a delay before release does not prove that the payment network itself is slow.
For a clear timeline, keep the request confirmation and any later status updates. Note when the request was submitted and when the operator marks it released. Those two points let you separate time spent awaiting release from time spent in transit, without treating them as one continuous payment operation.
In Australia, the legal context also matters: the Interactive Gambling Act 2001 prohibits operators from supplying real-money online casino games, including slots and table games, to people located in the country. The process described here is a general explanation of how approval and payment release differ; it is not an endorsement or an invitation to use a real-money casino service.
How PayID transfers work in Australia
PayID is an Australian bank-to-bank payment route. It operates through the New Payments Platform (NPP), which enables funds to move between bank accounts in real time. The Osko network processes PayID transfers in real time, providing the payment infrastructure behind the route.
For a withdrawal, PayID is the route used to send funds after the casino has released the payment. It does not decide whether a request is approved, nor does it move a pending request forward while the casino is still reviewing it. The distinction is between the casino’s decision to send the funds and the bank-to-bank transfer that follows. Real-time infrastructure applies to that transfer stage; it should not be read as a promise that a withdrawal request reaches your account immediately.
The process described for a PayID withdrawal is straightforward: log in, open the Wallet or Withdrawal area, enter a PayID identifier, specify the amount and confirm the transaction. In practical terms, this gives the payment process the destination information it needs. The transfer can then use the NPP pathway, with Osko handling real-time processing between banks. The identifier is part of directing the payment; it is not itself the transfer network.
How a PayID withdrawal is requested
Log in to your account, open the Wallet or Withdrawal area, enter your PayID identifier, specify the amount, and confirm the transaction.
This explains why a PayID payment can move quickly once it has been released, while the overall cashout may take longer. The network handles the movement of funds between accounts, but it does not replace the casino’s release decision. If a request has not yet been sent, the speed of the NPP and Osko stages cannot affect it. A description such as “instant” therefore refers to the payment phase, not necessarily the complete interval from submitting a request to seeing money in an account.
PayID’s role is also different from that of a card or a stored-value voucher. Here, the payment route is based on a transfer between bank accounts using Australia’s real-time payment infrastructure. That system-level function is what makes PayID relevant to a quick cashout; it does not establish how quickly a particular operator will handle a request, or whether it supports PayID withdrawals at all.
When reviewing a payment flow, identify where PayID enters the process. If it is offered as a withdrawal method, the casino’s instructions should specify the PayID details to enter and how to confirm the request. The transfer mechanism then concerns the route from the sender’s side to the receiving bank account. Do not treat a fast network as evidence that every step before release is also fast.
There is an important Australian context: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including slots, to people physically in Australia. A description of PayID’s payment infrastructure is not an endorsement or an invitation to use a real-money casino service. The technical point is narrower: PayID uses the NPP, and Osko processes transfers in real time once a payment is sent. That mechanism explains the transfer stage, not the legality of a service or the time required for a casino to release funds.
Limits, fees and the details to check before withdrawing
A withdrawal limit determines how much can leave an account in one request; it does not, by itself, determine when the money arrives. Casino policy may set a minimum and maximum for each transaction, and separate caps may restrict the total paid out over a week or month. These rules can change the amount you can request now and whether a remaining balance must be withdrawn later.
A specialist review reports that some PayID casinos publish minimum and maximum withdrawal limits. Treat that as a prompt to inspect the terms for the specific service, not as a guarantee that every limit is easy to find or identical. The same review type notes that weekly or monthly cashout caps may sit alongside the per-transaction maximum. A request can therefore fit within the single-payment limit but still exceed the remaining allowance for the relevant period.
Read the limits as a set
Before submitting a request, check the minimum, the maximum per transaction and any overall cap across a stated period. Also look for how the operator defines that period and what happens when a request is larger than the permitted amount. The terms may require a smaller request or divide a larger withdrawal into instalments under the operator’s policy. Either arrangement changes how many separate payments are needed; it should not be mistaken for a change in the payment method’s transfer speed.
Check whether the stated figures apply to all withdrawal routes or vary by method. A limit shown for one route may not apply to another. If the terms do not clearly connect a limit to the method you intend to use, the amount eligible for that request is uncertain until the operator clarifies it.
Check what can be deducted
A fee affects the amount that reaches you, even if it does not change the withdrawal request itself. A report by filmink.com.au says a transaction fee may apply when withdrawing through PayID. That does not establish that every PayID transaction carries a charge. Look for whether a fee is imposed, who applies it, and whether it is deducted from the requested amount or charged separately. If the terms do not explain the calculation, do not assume the amount paid out will equal the amount entered.
Consider the difference between a casino charge and a charge associated with the payment route. They may be described in separate parts of the terms. Reading only the withdrawal page can miss a fee stated elsewhere, while reading only the payment-method description can miss an operator-imposed deduction.
What to verify before confirming
Keep the relevant terms together: the minimum and maximum per request, any weekly or monthly cap, possible fees, and the treatment of requests that exceed a limit. Then compare those conditions with the amount you plan to withdraw. This lets you estimate the payable amount and identify whether the request may need to be split, without assuming that a fast route overrides the operator’s rules.
These are practical checks, not an endorsement of a service. Under Australia’s Interactive Gambling Act 2001, providing real-money online casino games to people in Australia is illegal. Any description of withdrawal terms should be read as information about stated conditions, not as an invitation to use such a service.
Real-money withdrawals and matching payment details
A withdrawal route is not always a free choice made at the end of a session. Operators generally require funds to be returned through the deposit method when that route supports withdrawals. This links the outgoing payment to the way money entered the account and helps keep the transaction within the operator’s payment rules.
That distinction matters because a deposit option may not be able to receive money back. A prepaid voucher, for instance, can be designed for adding funds rather than receiving a payout. If the original route cannot accept withdrawals, the operator may specify an alternative method. The available choice therefore depends on the payment terms, not simply on which transfer method appears fastest.
Keep the payment details consistent with the player profile. If you deposited using a PayID identifier, use the same PayID details for a withdrawal where the operator permits that route. A different identifier, bank account or account holder can make the destination appear unrelated to the profile. The payment may then be held for a security review or rejected under the operator’s rules. Use only accounts linked to the profile, and do not enter another person’s details as a substitute.
Attention Using a different identifier, bank account, or account holder than the one in your profile can lead to security reviews or rejected payments.
Before submitting a request, compare the selected withdrawal method with the deposit record and the account information saved in the profile. Check spelling and account identifiers carefully: a payment sent to the wrong destination may be difficult to recover, and correcting the details can require a new request. If the original method is unavailable for withdrawals, follow the operator’s stated alternative process rather than guessing which route will work.
This is a question of payment-route consistency, not a way to bypass identity checks or guarantee a shorter wait. A compatible destination can prevent avoidable mismatches, but it does not determine when an operator will approve a request or how quickly a payment provider will complete it. Those are separate parts of the process.
In Australia, real-money online casino services are prohibited for operators under the Interactive Gambling Act 2001. The practical point about matching payment details describes a general payment-control principle; it is not an invitation to use an offshore casino.
How to assess claims about fast withdrawals
A stated payout speed is meaningful only when you know which part of the process it measures. “Instant” may describe the transfer after approval, not the time from submitting a request to receiving funds. Automatic approval is a separate step: it means a request can pass an operator’s review without a manual decision, subject to the operator’s rules. Neither phrase, on its own, establishes how long the complete process will take.
Treat precise speed figures as reported results, not guarantees. One specialist review reported PayID withdrawals taking under five minutes and standard bank transfers taking one to three business days. Another specialist review put some PayID results in the range of 30 to 90 seconds on average. Those figures describe what the reviews observed or reported; they do not show that every request will follow the same timing. Averages also conceal variation between individual transactions.
Check what the clock starts and stops at. A payment-time claim may begin only once a withdrawal has been approved and released. If the request is awaiting review, the transfer clock may not have started. A claim about end-to-end time should state whether it includes approval, any security review and the payment provider’s transfer stage. If those boundaries are unclear, the headline figure is not enough to predict when funds will arrive.
Automatic approval claims need similar care. A specialist review reported that some higher-tier services automatically approved withdrawals below $5,000 AUD. That is a reported threshold, not a general rule or a promise that a request will be approved. Published conditions can still exclude requests that require extra checks, and automated handling does not remove the distinction between approval and transfer.
For a fair comparison, look for the method covered, the stage being timed, any stated conditions and whether the figure is an average or a maximum. Then compare like with like: an approval time cannot be compared directly with a bank’s transfer time. In Australia, real-money online casino games are prohibited services when offered to people physically in the country, so speed claims about such services should not be read as an endorsement or an assurance of availability.
Why ‘no verification’ does not mean no checks
A claim that a real-money platform offers withdrawals with “no verification” should not be read as proof that identity checks will never occur. Casinos must verify a player’s identity before processing a withdrawal. A payment option may move money quickly after approval, but it does not remove that requirement.
Legal Warning Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia.
The check establishes that the person requesting the funds is the account holder and that the account information can be confirmed. If the operator needs documents, the withdrawal cannot proceed until the review is complete. The request may therefore pause even when the payment method itself supports rapid transfers.
A specialist review reports that first withdrawal requests often prompt a request for identity documents. Treat this as a possibility to prepare for, rather than a guaranteed sequence at every platform. The documents requested and the time needed to assess them can depend on the operator’s process and the information already on file.
Completing verification before you request a withdrawal can reduce this later friction. If the platform provides an account verification area, check which details it asks you to confirm and whether any documents remain outstanding. Use clear, current information that matches your account records; inconsistent details can create questions that need to be resolved before a withdrawal is considered.
This is different from a promise of instant withdrawal. “Instant” can describe the payment stage after the operator has approved and released funds. Identity verification sits before that stage, so a fast transfer route cannot make an unverified request immediate from submission to receipt.
In Australia, real-money online casino services are prohibited under the Interactive Gambling Act 2001. The verification process described here explains why a no-check claim should not be treated as a reliable guarantee; it is not an endorsement or recommendation to use such a service.
Online slots: checks that can interrupt a cashout
A slot session can end with a balance that appears ready to withdraw, but the cashout still has to pass the operator’s checks. These checks concern who controls the account and whether the requested payment can be processed; they are separate from the game result and from the speed of the payment route.
Identity review is a common interruption on a first withdrawal. Casinos must verify a player’s identity through KYC procedures before processing withdrawals. If the account has not been verified, the operator may pause the request while it completes that review. Completing verification before requesting a cashout can reduce this source of delay, but it does not remove the possibility of further checks.
The amount requested can also affect handling. A specialist review identifies withdrawals above $2,000 as a possible reason for additional review. This is a reported trigger, not a universal threshold or a promise that requests below it will be approved automatically. Market requirements also call for manual review to be disclosed for withdrawals exceeding that amount. Check the operator’s terms for how such a review is handled rather than assuming that a payment method’s transfer speed determines when the money will arrive.
A specialist review also lists first-time KYC checks and bank processing windows among possible causes of delay. These are different stages: identity review happens before the operator can process a withdrawal, while a bank’s processing window can affect delivery after the request has moved beyond the operator’s checks. An “instant” label on a payment route therefore does not mean every request is checked and received immediately.
For Australian readers, there is a further boundary: providing real-money online slot games to people in Australia is prohibited under the Interactive Gambling Act 2001. This explanation describes how checks can affect a cashout; it is not an offer or recommendation to use an online casino.
If a request is paused, look for a status message or a request for information in the account, then contact the operator through its stated support channel if the reason is unclear. Avoid submitting repeated withdrawal requests while one is under review: a second request does not complete the first check. The useful distinction is whether the hold concerns identity, an additional review of the amount, or the receiving bank’s processing.
How do you choose the best easy withdrawal casino site?
Check that your preferred payment method is supported for withdrawals, then compare the stated processing times, fees and withdrawal limits. Completing identity verification early can help avoid delays, and published limits make it easier to assess cashout conditions.
What payment methods are available?
Reported options include credit and debit cards, PayPal and Skrill, and bank transfers; some platforms also offer cryptocurrency or instant banking services such as POLi. A method listed for deposits may not be available for withdrawals, so check the outgoing payment options.
How fast are withdrawals?
Timing depends on both the operator’s review and the payment route: e-wallet withdrawals are typically processed within 24 hours, while bank and card payments can take several days, with traditional bank transfers reported to take up to five business days. PayID withdrawals can be near-instant once released, but an operator’s review can still delay payment.
What are easy withdrawal casinos?
They are platforms where cashouts can be requested through supported methods and where processing times and withdrawal limits are clearly stated. In Australia, note that the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country.
Written by the editors at Lucky elf Casino.