Instant PayID Withdrawals in Australia: How They Work
 Available in AU
PayID can move funds in real time after an operator releases a withdrawal, but approval and payment checks happen first.
Table of Contents
- How PayID withdrawals move from casino approval to your bank
- What to check when assessing PayID cash-out speed
- What happens after you request a PayID withdrawal
- Withdrawal limits, fees and cash-out rules
- How PayID compares with other withdrawal methods
- Why a PayID withdrawal can take longer than expected
- Verification and payment-method checks before payout
- Payment options available to Australian players
- PayID withdrawals when playing pokies online
- Bonus conditions to clear before a pokies cash-out
How PayID withdrawals move from casino approval to your bank
“Instant” describes the transfer stage, not the entire time between asking for a withdrawal and seeing money in your account. PayID is Australia’s bank-to-bank payment system, operating through the New Payments Platform (NPP). Once a payment has been released and sent through the real-time payment process, the funds can move to your bank without the delay associated with a separate manual transfer between institutions.
A withdrawal therefore has distinct stages. First, a payment request exists with the operator. Then the operator must approve and release it. Only after release does the bank-to-bank transfer stage begin. PayID’s role is in that final movement of funds; it does not itself approve the request or determine when an operator releases money.
This distinction matters when you read a claim about an instant PayID withdrawal in Australia. A specialist review has described funds as moving instantly after a casino releases a withdrawal. That statement concerns the payment phase, not the full process from submitting a request to receiving cleared funds. If the request is still awaiting the operator’s action, the NPP cannot make that earlier stage instantaneous.
If you’re looking for instant PayID withdrawals in Australia, check the available payment and payout details carefully: a casino’s licence or deposit minimum does not establish how quickly PayID withdrawals are processed. Use these cards to see which operator details are available before choosing.
License: Curacao · Min. deposit: A$20 (POLi) You can note that Lucky Dreams is licensed in Curacao and lists a minimum deposit of A$20 via POLi. No PayID withdrawal speed is specified here.
License: Curacao OGL/2024/1335/0780 · Min. deposit: EUR 20 Vegaz Casino lists Curacao licence OGL/2024/1335/0780 and a minimum deposit of EUR 20. These details do not specify its PayID withdrawal availability or speed.
License: Curacao The available detail for Golden Pokies is its Curacao licence. No deposit minimum or PayID withdrawal information is provided.
License: Curacao eGaming (Roby Games Ltd) Roby Casino is identified as licensed by Curacao eGaming, with Roby Games Ltd named. No PayID withdrawal details are available here.
Payout speed: crypto under 1 hour, PayID 1-3 business days · Min. deposit: A$20 (A$30 to qualify for the bonus) Ricky Casino lists crypto payouts as taking under 1 hour, while PayID payouts are listed at 1–3 business days. Its minimum deposit is A$20, or A$30 to qualify for the bonus.
License: Curacao eGaming (Hollycorn N.V., since 2017) · Min. deposit: A$20-30 (depends on the offer) Playfina Casino is licensed by Curacao eGaming under Hollycorn N.V., which has held the licence since 2017. Its minimum deposit is A$20–30, depending on the offer; no PayID payout speed is specified.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) LuckyVibe is listed under Curacao Gaming Control Board licence OGL/2023/176/0095, held by Hollycorn N.V. The available details do not establish its PayID withdrawal speed.
License: Curacao (operating since 2017) · Min. deposit: A$20 Uptown Pokies is described as operating since 2017 and licensed in Curacao, with a minimum deposit of A$20. No PayID withdrawal timing is provided.
License: Curacao Gaming Control Board JustCasino is listed with a Curacao Gaming Control Board licence. The available information does not specify its deposit minimum or PayID withdrawal details.
License: Curacao Gaming Control Board OGL/2023/174/0082 (Dama N.V.) SpinsUp is listed under Curacao Gaming Control Board licence OGL/2023/174/0082, held by Dama N.V. No PayID withdrawal speed is specified.
What happens in the payment phase
PayID payments are processed in real time through the Osko network. In practical terms, once the operator has released a withdrawal into this payment route, the transfer can proceed between bank accounts in real time. The speed of that bank-to-bank stage should not be confused with the speed of the system that decides whether a withdrawal is ready to be sent.
You can think of the process as a hand-off. Before release, the funds remain under the operator’s control within its withdrawal process. At release, the payment is sent using PayID. The receiving bank then handles the incoming transfer. PayID and the NPP provide the real-time payment infrastructure for that hand-off; they do not make the operator’s preceding decision on your behalf.
This is why two descriptions that sound similar can mean different things. “The transfer is real time” refers to the payment network’s function. “The withdrawal is instant” could be read as a claim about the whole journey, from request through approval to receipt. Only the first meaning follows from PayID’s payment role. The timing of the earlier steps is separate.
A PayID identifier is used as part of addressing a payment, but the method should not be treated as a shortcut around the operator’s release process. Entering payment details or submitting a request does not itself send money to your bank. The key event is the operator’s release of the payment. Until that happens, the real-time transfer stage has not started.
Reading “instant” precisely
When a real money platform describes PayID as instant, identify which stage the description covers. If it refers to the transfer after release, it is describing the NPP payment route. If it implies that a request will be approved and received immediately, it combines separate stages and overstates what the payment network does.
The same distinction applies when you follow a withdrawal’s status. A request that has not been released is still on the operator side of the process. A released payment has moved into the payment stage, where PayID and Osko support real-time processing. These are different states, even if a screen uses broad labels such as “pending” or “processed.” The label alone does not explain whether the operator has approved the request or whether the bank transfer has begun.
There is also an important legal context for Australian readers. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including slots and table games, to people physically located in Australia. A technical explanation of PayID does not make such a service lawful or endorse its use. The payment mechanism and the legality of the underlying activity are separate questions.
The useful interpretation is narrow: PayID is the bank-to-bank route, and its real-time capability applies after a payment has been released into that route. It does not promise instant approval, remove the operator’s role, or guarantee that every step from request to bank receipt happens at once.
Legal Warning
The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including slots and table games, to people physically located in Australia.
What to check when assessing PayID cash-out speed
A PayID speed claim is useful only if the terms explain what is being timed. Check whether the stated period covers the casino’s handling of a request, the transfer after release, or both. “Instant” can describe the payment phase without meaning that money will arrive immediately after you submit a withdrawal request. If the terms do not define the clock, the claim is difficult to compare with another provider’s estimate.
A specialist review has reported PayID withdrawals taking under five minutes at some Australian-facing casinos, while standard bank transfers were listed at one to three business days. Treat those figures as that review’s reported results, not as a general service standard or a promise about a particular withdrawal. Published terms are more relevant to your decision than a broad speed label: look for a stated processing window and any wording that allows requests to take longer.
Then check whether the time is described as a target, an average, or a maximum. Those terms are not interchangeable. A target indicates an intended service level; an average summarises observed cases but does not tell you how long an individual request may take; a maximum sets a boundary only if the terms make it clear what circumstances can extend it. If the operator gives no definition, do not assume that “instant” guarantees a fixed arrival time.
The withdrawal limits are also part of assessing whether the advertised speed applies to the amount you intend to cash out. A specialist review reports that reputable PayID casinos publish minimum and maximum withdrawal limits clearly. Check both, and look for any separate rule that changes the permitted amount or handling for a particular request. A speed claim may be less useful if your intended withdrawal falls outside the stated range or is split under the operator’s policy. The relevant figures should be in the payment terms, not left to inference from a headline.
Compare like with like. A PayID estimate and a bank-transfer estimate may describe different stages or use different timing labels. Record the method, the period stated, the event that starts the clock, and any qualifications attached to the estimate. This gives you a more reliable comparison than relying on “fast” or “instant” alone.
There is also a legal limit to how this information should be used in Australia: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. Speed comparisons do not make such services lawful or constitute a recommendation to use them. Read claims as descriptions, not guarantees, and do not treat an advertised payout time as proof that a withdrawal will be completed within that period.
What happens after you request a PayID withdrawal
A withdrawal request and a bank transfer are separate events. Submitting a request tells the operator what amount you want paid and where to send it. The operator must then approve and release it. Only after release does the PayID transfer stage begin, so an instant payment method does not make the full process instant from request to receipt.
Where an operator provides a PayID withdrawal option, the request flow may involve signing in, opening the Wallet or Withdrawal area, entering the PayID identifier linked to your account, specifying an amount and confirming. The request then enters the operator’s system; it is not yet a payment instruction moving through the banking network.
Requesting a Withdrawal
Log in to your account and open the Wallet or Withdrawal area.
Enter your PayID identifier linked to your account and specify the withdrawal amount.
Confirm the details to submit the request to the operator’s system for review.
The operator’s review determines whether the request can be released. It may check account details, payment eligibility and any outstanding account requirements. Casinos must complete identity checks before processing withdrawals, and the money should go only to an account linked to your casino profile. If the request needs further review, its status can remain pending even though PayID itself supports real-time transfers.
Once approved, the operator sends the payment to the nominated PayID. PayID operates through Australia’s New Payments Platform, with transfers processed in real time through Osko. In practical terms, the near-instant part refers to this transfer after release—not to the time between clicking “withdraw” and seeing the funds arrive. The operator’s release time and the bank transfer time are distinct parts of the journey.
Published performance claims should be read with that distinction in mind. A specialist review reported withdrawal processing averages of 30–90 seconds for the options it assessed. That figure describes reported results in that review, not a fixed timetable that applies to every request or operator. A separate specialist review noted that some services promoted “instant” withdrawals while internal review kept requests pending for as long as 24 hours. These reports illustrate why a speed claim needs to be tied to the stage it measures.
A useful status sequence is therefore: request submitted, operator review, approved or released, then payment received. If the request is still awaiting approval, the delay is not evidence that the PayID network is taking that long. If it has been released but has not appeared, the transfer stage is the relevant point to query.
Real-money online casino games, including slots and table games, are prohibited interactive gambling services when provided to people in Australia under the Interactive Gambling Act 2001. The process described here explains payment stages; it does not imply that such services may lawfully be offered to Australian residents.
Withdrawal limits, fees and cash-out rules
The amount available through PayID is governed by the operator’s cash-out rules, not by the payment identifier itself. A withdrawal policy can set a minimum amount, a maximum for each request and a separate cap on total withdrawals over a stated period. These limits answer different questions: the per-transaction maximum controls the size of one cash-out, while a cumulative cap controls how much can leave the account across multiple requests during the relevant period.
That distinction matters when a balance exceeds the single-request maximum. The operator’s policy may require the amount to be divided into separate withdrawals, and larger withdrawals may be released in instalments. Splitting a balance does not necessarily bypass a cumulative cap: if the total requested amount reaches that cap, further cash-outs may have to wait until the relevant period resets. A specialist review has reported that some operators set weekly or monthly limits in addition to per-transaction maximums; the actual terms depend on the operator.
Check how the policy defines its period. A weekly cap, for instance, could be calculated by calendar week or by a rolling period, and the wording should explain which applies. Also look for whether the limit is measured against requested withdrawals or completed payouts. If the terms do not make the calculation clear, ask the operator to explain it before relying on a particular amount being available.
- Compare single-request limits with cumulative caps
- Check if a weekly cap is based on a calendar or rolling period
- Verify if fees are fixed or percentage-based
- Assume a displayed balance can be withdrawn in one request
- Assume repeated requests are treated independently
- Rely on a headline balance without checking net payout rules
A specialist review has also reported that withdrawal amounts can be restricted by operator policy. The practical check is therefore to compare the minimum and maximum for a single PayID cash-out with any cumulative cap, then consider how the rules apply to the amount you intend to withdraw. Do not assume that a displayed account balance can be withdrawn in one request or that repeated requests are treated independently.
Fees are a separate part of the calculation. A report by filmink.com.au notes that a fee may apply to a PayID withdrawal. That does not establish that every operator charges one, or that any charge is a PayID network fee. The terms should identify whether a fee applies, what triggers it and how it is deducted. A fixed charge reduces the amount received by the same amount regardless of the cash-out size; a percentage-based charge changes with the amount. If the policy does not state the basis clearly, the net payout cannot be calculated reliably from the headline balance alone.
Before submitting a request, read the cash-out terms as a set: per-request minimum and maximum, any weekly or monthly cap, rules for instalments, and applicable fees. These are amount and cost conditions, distinct from the time taken to process a request or transfer funds. An “instant” label does not override them: it describes neither how much you may withdraw nor whether the full balance can be paid in a single transaction.
How PayID compares with other withdrawal methods
Withdrawal timing depends partly on the route used to send the money. PayID uses Australia’s New Payments Platform, so the bank-to-bank transfer can occur in real time once the sender releases it. That describes the transfer stage, not how long an operator takes to review a request. By contrast, card and bank-transfer payouts pass through processes that can take several days.
E-wallets sit between those routes in many published timing estimates. PayPal and Skrill are examples available to Australian players according to specialist reviews of casino payment options. Those reviews describe e-wallet withdrawals as typically processed within 24 hours. This is an estimate for the withdrawal process, not a guaranteed arrival time: the operator’s handling and the wallet provider’s own processing both matter.
For bank transfers, published estimates vary. Specialist reviews report that traditional transfers can take as long as five business days to complete. A separate general estimate places bank transfers and card payments at several days. These figures describe reported processing windows, not a fixed timetable for every provider or transaction. A card payout may therefore be slower than a completed PayID transfer even when both are requested from the same account.
| Method | Reported timing | What the timing describes |
|---|---|---|
| PayID | Real-time transfer after release | The bank transfer stage, once funds are sent |
| E-wallets | Typically processed within 24 hours | A reported withdrawal-processing estimate |
| Cards | May take several days | A reported payout-processing estimate |
| Traditional bank transfer | Several days; specialist reviews report up to five business days | A reported transfer-completion window |
The table is useful for comparing routes, but the labels are not interchangeable. “Processed” can mean the operator has approved and sent a payment; “completed” can mean the funds have arrived. PayID’s advantage is specifically its transfer stage after release. It does not turn the entire request-to-receipt process into an instant one.
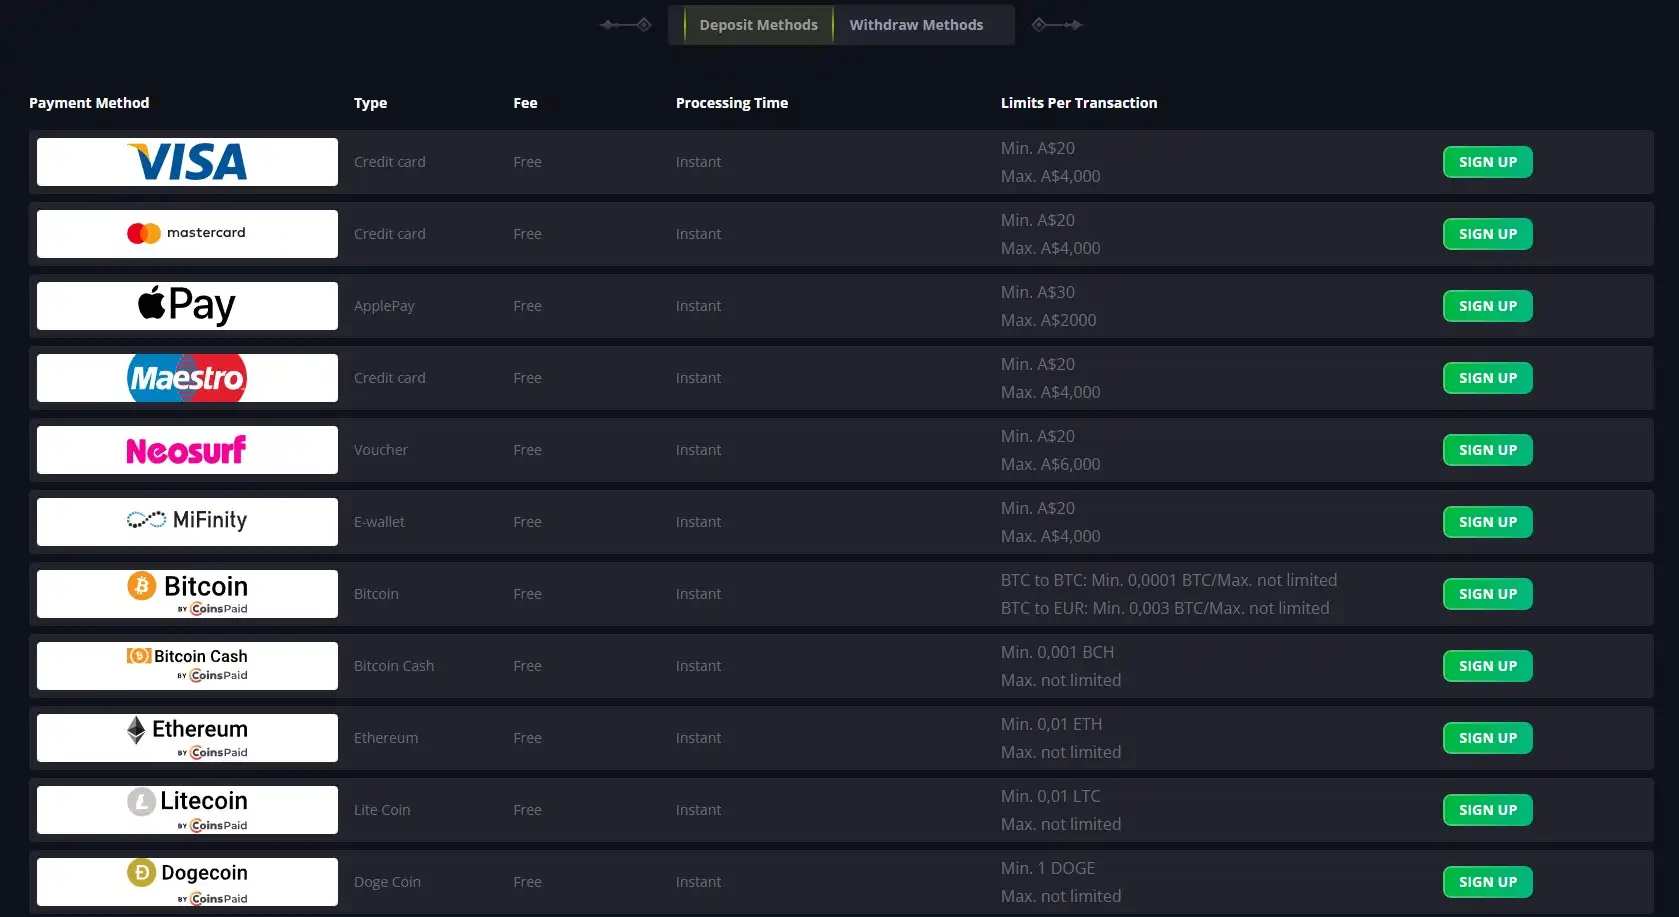
The payment options described in specialist reviews for Australian players include credit and debit cards, PayPal and Skrill, and bank transfers; some reviews also mention cryptocurrency. Availability depends on the service and account, so a method appearing in a general list does not mean it is offered for every transaction. These comparisons are informational, not an endorsement: Australian law prohibits operators from providing real-money online casino games to people in Australia.
When comparing stated times, check what event starts the clock and what event stops it. A claim about the payment network’s speed is not the same as a promise about when a withdrawal request will be approved or arrive. PayID can make the final bank-transfer stage rapid; the other methods have their own processing routes and stated windows.
Comparison Summary
- PayID offers real-time bank transfers specifically after the operator releases the funds
- E-wallets are typically processed within 24 hours
- Traditional bank transfers and cards can take several days to complete
- The total time from request to receipt depends on the operator’s internal review speed
Why a PayID withdrawal can take longer than expected
PayID can transfer money in real time through Australia’s New Payments Platform, but that describes the bank-to-bank payment after the sender releases the funds. It does not mean a withdrawal request is approved and credited at the same moment. The overall wait includes any operator-side review and the bank’s handling of the released payment.
A specialist review identifies several possible sources of delay, including first-time identity checks, larger withdrawal requests and bank processing windows. These are separate stages: a transfer may be ready to move through PayID but still be waiting for a decision or for the receiving bank to process it. An “instant” label therefore needs to be read as a description of the transfer phase, not a promise about the entire request-to-receipt process.
A first withdrawal can take longer when identity documents have not yet been checked. If a review is required, the request remains pending while the operator examines it; the speed of the later PayID transfer cannot remove that earlier wait. Completing verification before requesting a withdrawal can reduce the chance that this step begins only after the request is submitted.
The amount can also affect the review path. A specialist review lists withdrawals over $2,000 among possible causes of delay. Where an operator requires manual review above that threshold, its terms should explain the process. A larger request may therefore wait for approval even though PayID itself can carry the payment in real time. Do not assume that splitting a request will avoid a review; the operator’s rules determine how requests are assessed.
Bank processing windows are another distinct factor. If the operator has released the funds but they have not appeared in the linked account, the remaining wait may sit with payment handling rather than approval. Check the withdrawal status first: “pending” points to an unfinished operator stage, while a status indicating release means the transfer has moved beyond that stage. If the status is unclear, ask the operator whether it has sent the payment and contact the bank if needed.
Status Meanings
A “pending” status typically indicates the request is still with the operator, while a status indicating release means the funds have moved into the bank transfer stage.
For an instant PayID withdrawal, the useful question is not simply how quickly PayID transfers funds. It is whether the request is awaiting checks, has been released, or is still being processed by the bank. These stages explain why two withdrawals using the same payment method can reach an account at different times. In Australia, real-money online casino services are prohibited under the Interactive Gambling Act 2001; this explanation does not endorse or promote their use.
Verification and payment-method checks before payout
Identity checks and payment-method checks answer different questions. Identity verification establishes who controls the account; matching payment details helps an operator confirm that funds are being returned through an eligible route. Neither check is the bank transfer itself, so completing them does not change how PayID moves money after a payment is released.
A specialist review reports that first withdrawals can prompt identity-verification requests. Casinos must complete KYC checks before processing withdrawals. If a request arrives, the withdrawal may remain pending until the operator has received and accepted the required information. The exact requirements depend on the operator’s process, so read its instructions carefully and submit information through the account’s stated verification channel.
You can reduce avoidable back-and-forth by completing any available identity checks before requesting a payout. Early verification can significantly speed up later withdrawals because the operator has already checked the account before a cash-out is waiting to be processed. Keep your account details consistent and respond to any follow-up request; an incomplete check can still hold up a later payment.
Payment details need attention too. Operators generally require funds to be returned to the same method used for the deposit where possible. For PayID, that means using the same PayID details associated with the deposit rather than entering a different identifier at withdrawal. A mismatch can prompt a security review because the operator has to establish that the destination is connected to your casino profile and is an appropriate place to send the funds.
Before submitting a request, check that the PayID details you intend to use match those on the account and that the receiving account is linked to your profile. If you deposited through a different method, check the operator’s payment rules rather than assuming PayID can be substituted freely. A payment route may be available for deposits but not accepted for withdrawals, or the operator may require the original method where possible.
The practical preparation is simple: complete KYC early, keep profile and payment details consistent, and use only an account linked to the profile. If any detail has changed, resolve it with the operator before requesting a payout. That is more predictable than discovering a mismatch after the withdrawal is waiting for review.
These checks explain why “instant” does not mean immediate from request to receipt. It describes the payment phase after approval, not identity review or confirmation that the destination details are acceptable. In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. This description is informational and does not promote access to such services.
Pre-Payout Checklist
- Complete all KYC and identity verification requirements early
- Ensure the PayID identifier matches the one used for deposits
- Confirm the receiving bank account is linked to your profile
- Verify that no outstanding bonus wagering requirements remain
Payment options available to Australian players
Payment menus reported for Australian-facing real-money casino services include bank transfers, e-wallets, card payments, instant banking and, in some cases, cryptocurrency. These descriptions concern payment methods, not a statement that such services are lawful to provide in Australia. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games to people physically located in the country.
Bank transfers send funds between accounts, while an e-wallet holds payment details separately from the bank account used to fund it. PayPal and Skrill are examples of e-wallets identified in specialist reviews of payment options. Whether a particular method appears in a cashier, and whether it can be used for a withdrawal as well as a deposit, depends on the service’s own payment rules.
Card listings require particular care. Some reviews mention credit and debit cards, but credit card payments must not be accepted for online gambling services. A card appearing in a general payment-method list does not establish that it can lawfully be used for that purpose in Australia. Nor does a deposit method necessarily serve as a withdrawal route.
Instant banking is a separate category: a provider connects a bank account to a payment flow rather than acting as a stored-value wallet. Specialist reviews have reported that some services offered instant banking through providers such as POLi. That is a report about availability, not a guarantee that a provider or service remains accessible or that every transaction is immediate.
Cryptocurrency is also reported as an option by some specialist reviews. Those reviews describe the potential for near-instant transactions, but the transfer still depends on the payment route and the service handling it. The description should not be read as a universal processing time or as evidence that a casino service is legally available in Australia.
Prepaid vouchers such as Neosurf are described in specialist reviews as deposit methods, not withdrawal methods. If a voucher cannot receive funds, it cannot by itself provide a route for cashing out. This illustrates why payment menus should be read by transaction type: the options for adding funds may differ from those for sending funds back.
Across these categories, a method’s name tells you little about its actual role. Check whether it is listed for deposits, withdrawals or both, and distinguish a bank transfer from an e-wallet or an instant-banking connection. In Australia, the legal position on real-money online casino services remains separate from the technical capabilities of payment providers.
PayID withdrawals when playing pokies online
For a pokies cash-out, the payment route and the game balance are separate parts of the process. A balance shown in an account does not itself create a bank transfer. A withdrawal request must first be accepted and released by the operator; PayID concerns the movement of funds after that release.
A specialist review has described PayID transfers as near-instant, and reported that funds can move as soon as an operator releases a withdrawal. That timing applies to the payment stage, not necessarily to the full period from requesting a cash-out to seeing money in a bank account. If an operator has not approved or sent the payment, the real-time transfer mechanism has not yet begun. An “instant withdrawal” claim therefore needs to be read in that narrower sense, rather than as a promise of immediate receipt from the moment you submit a request.
Attention: A win in a pokies game changes your account balance but does not bypass the operator’s withdrawal review and release process.
The distinction matters with pokies because the game result and the cash-out are not the same transaction. A win may change the account balance, but it does not bypass the operator’s withdrawal process. Once the operator releases an eligible withdrawal to the PayID details linked to the account, the bank-to-bank payment stage can proceed rapidly. Until then, the balance remains within the operator’s system.
PayID is an Australian payment identifier used to route transfers between bank accounts through the New Payments Platform. It identifies the destination; it does not decide whether a withdrawal is approved or how quickly an operator handles a request. Nor does choosing PayID make a pending request an active bank transfer. The useful point of comparison is therefore the release time and the transfer time as separate stages, not a single headline speed.
There is also a legal boundary specific to Australian readers. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino-style services, including pokies, to people located in Australia. This section describes the payment mechanism, not an invitation to use such a service. A payment method’s availability does not change the rules governing the underlying activity.
If you encounter a reference to PayID for a pokies withdrawal, interpret it as describing how money may be routed after an operator releases it. It does not establish that the account balance is withdrawable, that a request has been approved, or that receipt is immediate from submission. The transfer can be fast while the overall cash-out remains pending at an earlier stage.
Bonus conditions to clear before a pokies cash-out
A PayID transfer cannot make bonus funds eligible for withdrawal if the applicable wagering requirement remains unmet. Treat bonus eligibility as a separate condition from the payment method: the bonus terms determine whether you can request a cash-out, while PayID concerns how an approved payment is sent.
A specialist review describes two possible bases for wagering requirements: the bonus funds alone, or the combined value of the deposit and bonus. The distinction affects how much qualifying play is required under the stated terms. A bonus-funds-only requirement is preferable because it does not include your deposit in the wagering base. Do not assume which structure applies; read the terms attached to the specific offer.
Before accepting or using a bonus, locate the wording that explains its wagering basis and what must be completed before withdrawal. Check whether the requirement applies to the bonus alone or to the deposit and bonus together. Then confirm whether the terms say that wagering must be complete before a cash-out request can be made. If the rule is unclear, do not infer that a balance shown in your account is fully withdrawable: it may include funds still subject to the offer conditions.
Track the requirement as you play and check the account’s displayed status against the written terms. If the requirement is not marked as complete, a withdrawal request may not be available or the operator may not release the funds. That is an eligibility issue, not a PayID delay. Requesting an instant withdrawal does not remove an outstanding bonus condition or change the basis used to calculate it.
Read the rules before opting into an offer, not only when you are ready to cash out. If you do not want bonus conditions to affect access to your balance, avoid accepting a bonus whose terms you do not understand. Where the terms allow a choice, compare the wagering base carefully: applying the requirement to bonus funds alone is preferable to applying it to the combined deposit and bonus.
In Australia, real-money online casino games, including pokies, are prohibited interactive gambling services when offered to people in the country. This explanation is not an invitation to use such a service. The practical point is that bonus terms can restrict whether funds are withdrawable; PayID does not override those terms.
What payment methods are available?
Available methods can include credit and debit cards, PayPal and Skrill, bank transfers, and—in some cases—cryptocurrency or instant banking services such as POLi. Neosurf and similar vouchers are generally for deposits, not withdrawals.
How do you choose the best easy withdrawal casino site?
Check whether the site clearly states its withdrawal processing times, PayID limits, fees, and any weekly or monthly cash-out caps. Complete identity verification early and check whether withdrawals are returned to your deposit method; PayID transfers are real-time only after the operator releases the payment.
What are easy withdrawal casinos?
They are sites that make cash-outs straightforward and process them quickly. With PayID, the bank transfer can be real-time after the operator releases the withdrawal, but that does not guarantee instant approval; real-money online casino games are prohibited for people physically in Australia.
How fast are withdrawals?
PayID transfers can move in real time after release, and a specialist review reported some withdrawals taking under five minutes. E-wallet withdrawals are often completed within hours or processed within 24 hours, while bank transfers can take several business days.
Created by the ”Lucky elf Casino” editorial team.